What Is the Chase 5/24 Rule? Everything You Need to Know
Loading article…
Chase’s credit card portfolio is one of the best out there.
The bank has a slew of great cobranded credit cards, ranging from Air Canada, British Airways and United MileagePlus to Marriott Bonvoy and World of Hyatt, in addition to iconic credit cards like the Chase Sapphire Preferred® Credit Card that earn valuable Chase Ultimate Rewards points.
That said, Chase is one of the more difficult banks to get a credit card with. This is because of a rule called “Chase 5/24” which has become notorious in the travel credit card world.
This rule means you will be automatically denied a new Chase card if you’ve opened five or more credit cards across all banks in the past 24 months. It’s not a published rule, but it has been widely reported on for years.
Thankfully, there are some exceptions to this rule and other important things to consider. Here, we’ll give you an in-depth look at the Chase 5/24 rule and discuss how to plan your credit card applications accordingly.
Short answer: As of September 2026, the Chase 5/24 rule is an unofficial but widely reported policy. If you have opened 5 or more personal credit cards with any bank in the past 24 months, Chase will usually decline a new application. Most business cards, like the Ink Business Preferred®, do not add to your count.
The Chase 5/24 rule means that, in most cases, you cannot be approved for a new Chase credit card if you’ve been approved for five or more new credit cards in the past 24 months.
This includes new credit cards across all banks, including Chase. However, car loans, mortgages, personal loans, and other loans do not count toward 5/24.
This frustrating rule applies to both personal and business Chase credit cards, so it’s essential for you to carefully plan out Chase credit card applications early in your credit journey.
If you’re already over 5/24, our team found that the timer resets at the beginning of the month following when you fall under 5/24. For example, if you opened a credit card on March 4, 2023, it would fall off your 5/24 status on April 1, 2025.
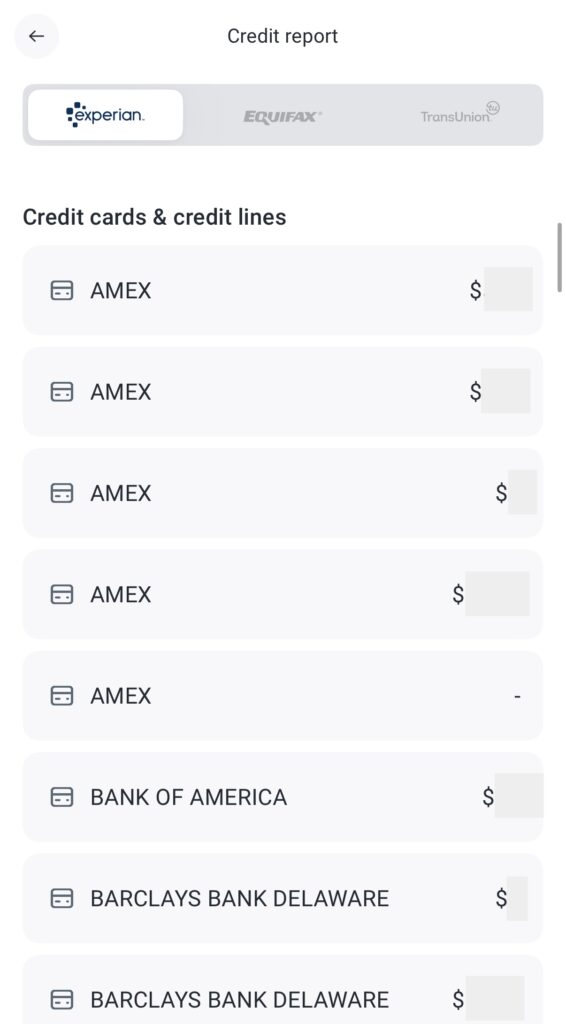
With this in mind, it’s essential to keep track of when you open new credit card accounts so you can keep tabs on your 5/24 status. You can also use the free Experian app to track when you open new credit card accounts. Head to the “Accounts” screen. Here, you’ll see your credit card accounts. You can view the day you opened them when you tap on the account. They are sorted in chronological order, starting with the newest account.
Thankfully, there are a couple of notable exceptions to Chase’s 5/24 rule.
Namely, most business credit cards do not count toward your 5/24 status, even business cards issued by Chase. Being over 5/24 will, however, prevent you from being approved for a Chase business credit card.
Unfortunately, Capital One small business credit cards do count toward 5/24 in most cases, since they’re listed like personal credit cards on your credit report. That said, business credit cards from American Express, Chase, Citi, and most other banks will not count.
It’s also worth noting that authorized user cards do not count toward 5/24, but it might prevent you from being automatically approved for a Chase card online. If you’re denied, call Chase and explain that you’ve been added as an authorized user to someone else’s card. They should be able to reconsider the application with this in mind.
Over the years, we’ve also seen reports of certain targeted and in-branch offers being excluded from 5/24. These offers can be few and far between, so don’t count on them when planning your Chase credit card strategy.
With the Chase 5/24 rule in mind, you should consider applying for Chase cards before cards from other banks. This gives you the freedom to be approved for high-value Chase cards without restriction. Then, you can move on to applying for cards from other banks.
This is especially important if you qualify for a small business credit card. You can apply for these cards first, and they won’t count toward your 5/24 status for other Chase credit cards if you’re approved.
Some Chase cards you might consider applying for first include:
| Credit card | Annual fee | Welcome offer | |
|---|---|---|---|
| $95 | |||
| $795 | |||
| $95 |
Earn Big on Travel with the Chase Sapphire Preferred® Card
Make every trip count. Transfer your points 1:1 to leading airline and hotel loyalty programs, or redeem them through Chase Travel℠ for 25% more value. You’re also covered by built-in travel protections like trip cancellation/interruption insurance, auto rental collision damage waiver and lost luggage insurance, with everything managed in the Chase mobile app. Whether you fly often or are planning your next getaway, the Chase Sapphire Preferred® delivers premium perks at an approachable price.
Terms apply. Bonus offer requires minimum spend. Annual fee applies. Member FDIC. See Chase for full details.
on Chase's website
Travel in Style with the Chase Sapphire Reserve® Card
From premium lounge retreats to robust trip protections (cancellation, interruption, auto rental and lost luggage insurance), this card lets you travel with confidence. Manage everything in the Chase app, tap to pay with contactless security, and let the automatic credits help offset the annual fee with high-value perks all year long.
Terms apply. Bonus offer requires minimum spend. Annual fee applies. Member FDIC. See Chase for full details.
on Chase's website
Maximize Business Travel Rewards with the Chase Ink Business Preferred® Credit Card
Reward everyday business spend—from shipping and advertising to telecom and travel—with elevated earning rates and seamless redemptions. Combine points across your Chase portfolio, redeem them for 1.25¢ each toward travel booked through Chase Travel℠, or transfer them to more than a dozen top loyalty partners. Stay in control with an intuitive dashboard, real‑time alerts and powerful digital tools built for busy entrepreneurs.
Terms apply. Bonus points require $8,000 spend in 3 months. Rewards cap at 150,000 bonus-category points per anniversary year. See issuer for full details.
on Chase's website
Chase’s infamous 5/24 rule is an unfortunate reality in the travel rewards world. It makes life difficult when you’re applying for new cards, but with some planning, you can still get the Chase cards you want.
Make sure to read our guide to the best Chase credit cards before you apply. Here, you’ll find the best offers and the Chase cards we recommend to those new to the travel rewards space.
The Chase 5/24 rule means you can’t be approved for most Chase credit cards if you’ve opened five or more credit cards from any bank in the past 24 months.
All personal credit cards from any bank count. Most business credit cards do not count, except for Capital One business cards, which typically appear on your personal credit report.
No, authorized user cards typically do not count. However, they might still trigger an automatic denial, so you may need to call Chase to explain your situation for reconsideration.
A card falls off your 5/24 count at the start of the month after the 24-month anniversary of opening the account. For example, a card opened on March 4, 2023, falls off on April 1, 2025.
Most Chase business cards do not count toward your 5/24 total. However, being over 5/24 will still prevent you from being approved for a Chase business card.
Yes, targeted and in-branch offers are sometimes exempt from 5/24, but these are rare and unpredictable. Business cards from most banks also don’t count toward 5/24.
It’s smart to apply for Chase credit cards early in your credit journey, before you reach 5/24. If you’re eligible, consider applying for business cards first, as they usually don’t affect your 5/24 status.
Our reviews and rankings are based on an objective assessment. Advertisers do not influence our content. We may receive compensation through some links; our analysis and opinions remain independent.